
How the 2027 FEHB premium increase will impact federal employees and annuitants
How the 2027 FEHB premium increase will impact federal employees and annuitants
By: Kevin Moss
Federal employees and annuitants will face a third straight year of double-digit Federal Employees Health Benefits (FEHB) premium increases in 2027. Though it’s less than previous years, the enrollee share of premium will go up an average of 10.9%. The Office of Personnel Management points to rising costs across the entire healthcare system, emphasizing increased usage in behavioral and mental healthcare and higher prescription drug spending, especially on GLP-1 weight loss drugs.
To help you prepare for Open Season, I’ll walk you through recent FEHB premium increases, show the distribution of changes across FEHB, highlight popular plans, provide enrollment advice for two-person families, discuss Postal Service Health Benefits (PSHB) premiums, and cover what to expect from Federal Employees Dental and Vision Insurance Program (FEDVIP) options.
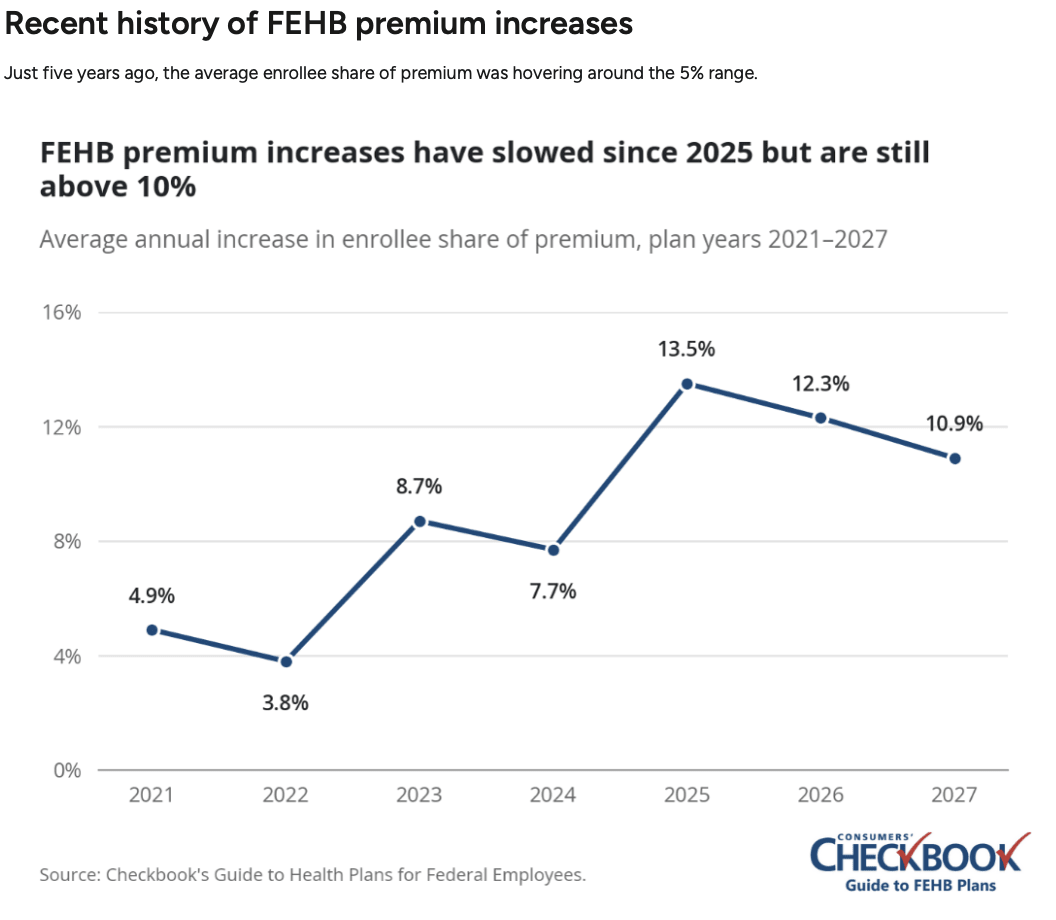
Healthcare inflation tends to run higher than overall inflation, so federal employees and annuitants should anticipate continued increases in the future.
These price hikes aren’t unique to FEHB however; plans under the Affordable Care Act have a 15% median premium increase planned for 2027, and those for large-group employers are set to go up around 9.5% next year.
How FEHB premiums are changing in 2027
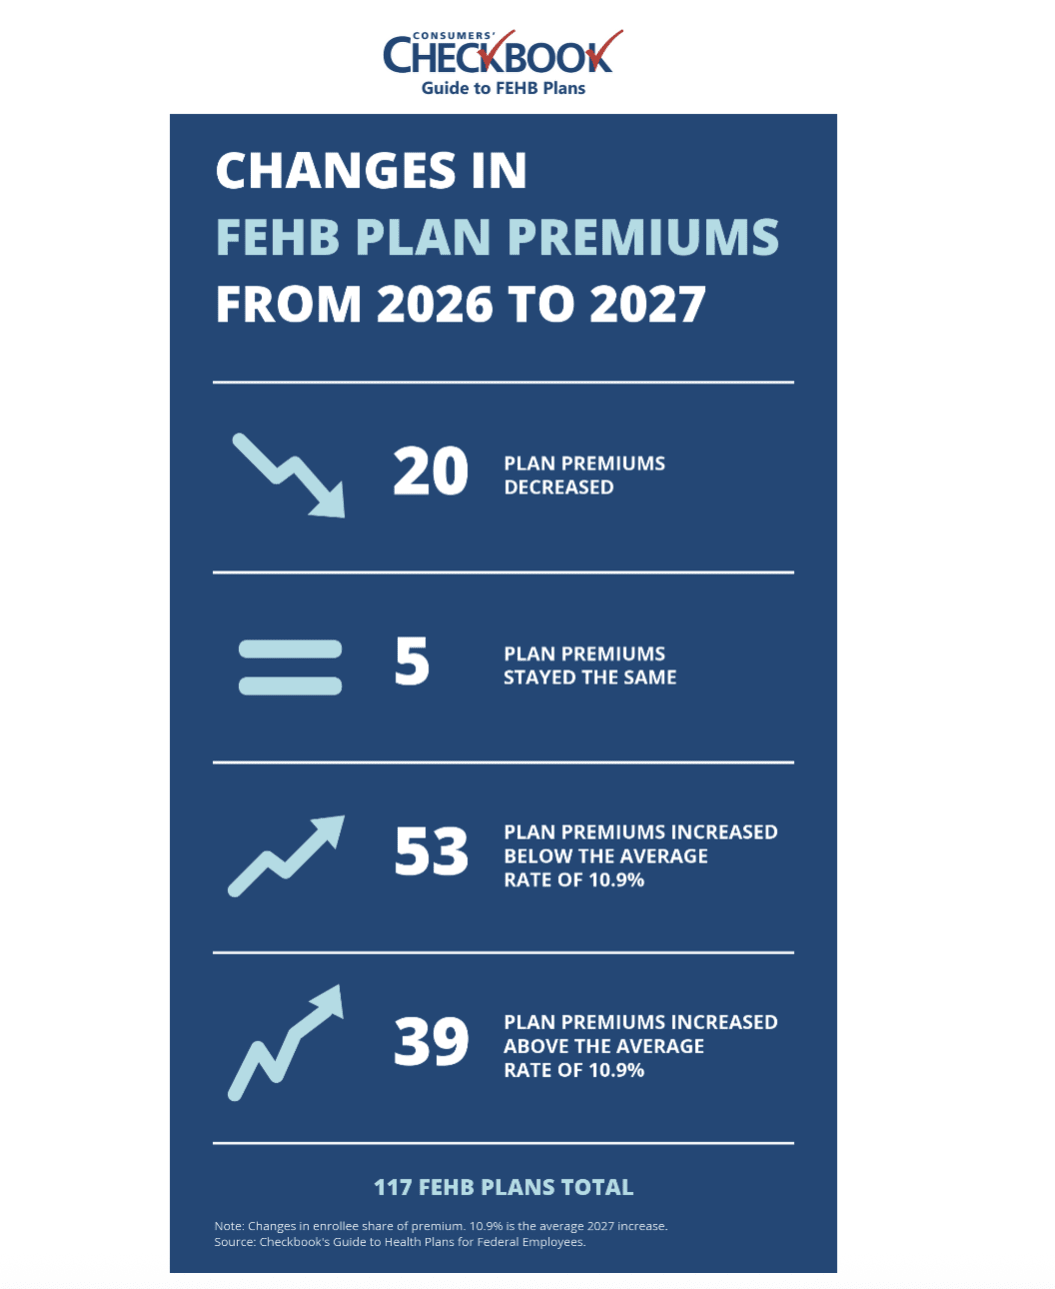
Not all plans reflect this trend. For the 117 FEHB plans available in both 2026 and 2027, self-only premiums will decrease in 20 of them, stay the same in 5, increase below the 10.9% average in 53, and increase above the average in 39.
Some of the changes are striking: The largest decrease in enrollee share is for M.D. IPA (JP1), available in the Washington, D.C. area, where the premium is decreasing 46%, saving self-only enrollees $2,626 next year. On the other hand, GEHA Standard will cost the same, and MHBP Standard (454) will have the largest increase at 63%, or $1,540 more per year for self-only enrollees.
How is your plan’s premium changing next year? Even if you’re happy with your existing coverage, it will likely be more expensive. That’s why it’s important to check. You can find your premium for next year on the OPM Open Season page or at the very back of the official FEHB brochure once it’s released. There may be another plan that offers better value.
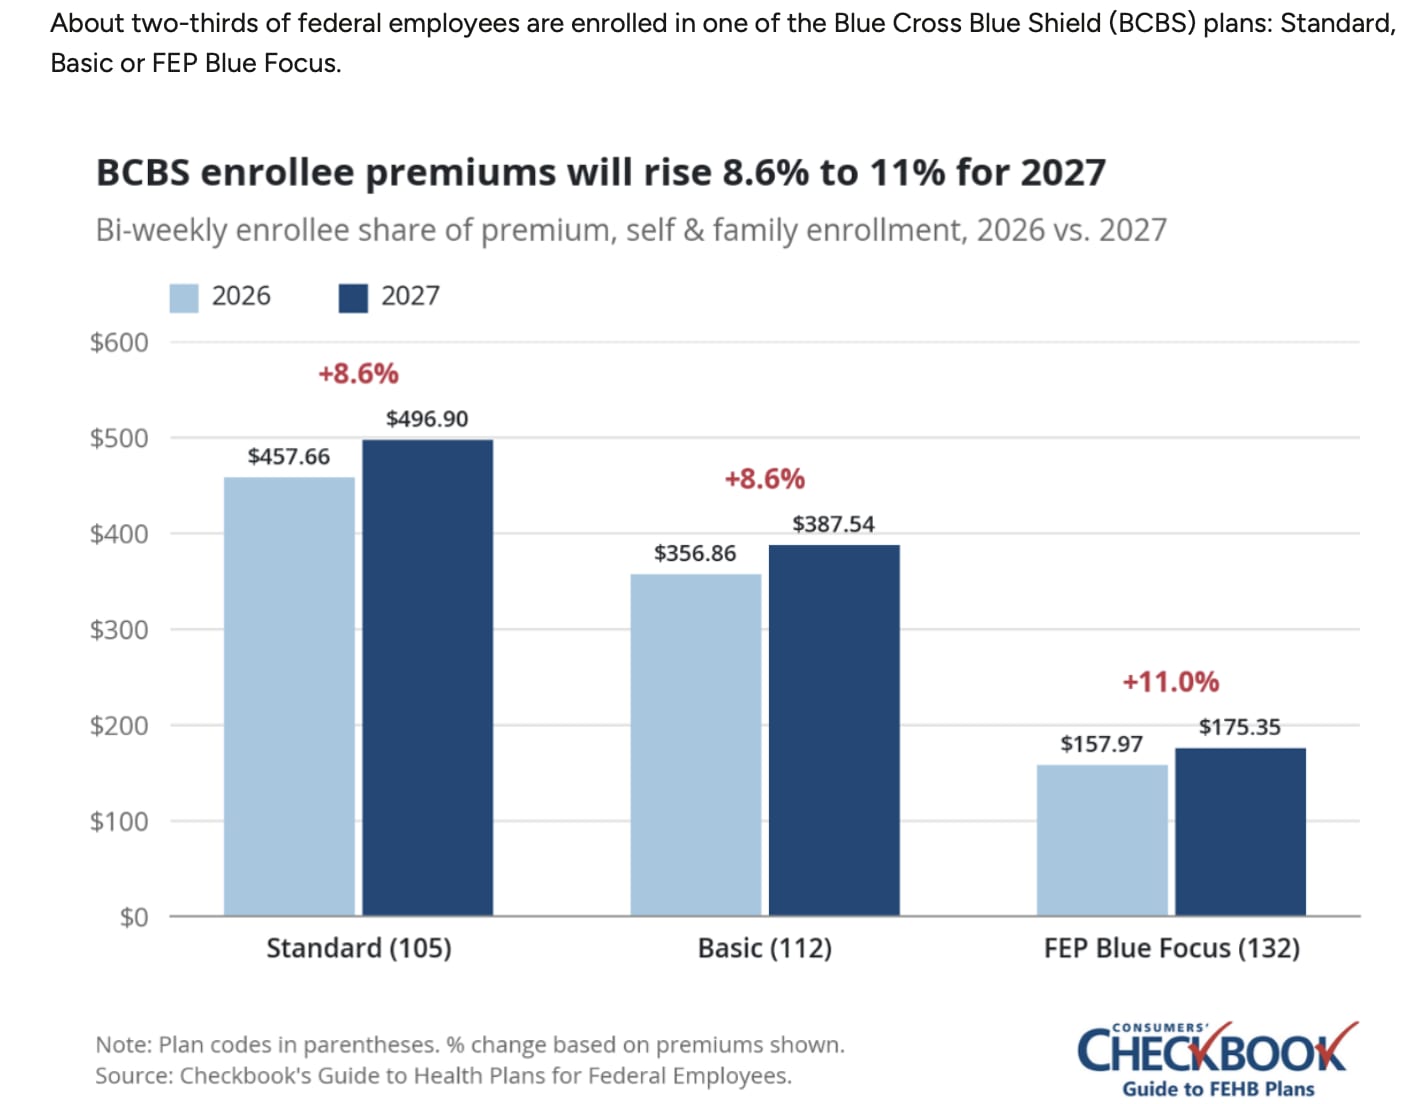
Basic and Standard both increased below the all-plan average, while FEP Blue Focus went up slightly more.
If you’re currently enrolled in a BCBS plan, when was the last time you evaluated the other two options? This upcoming Open Season is a good opportunity to assess whether your current selection is still the best fit.
There are many differences between Standard, Basic and FEP Blue Focus, but some of the most significant are that Standard is the only plan where:
- You can see out-of-network providers,
- Receive mail-order prescription drugs (Basic has mail-order prescription drug coverage only for annuitants with Part B),
- Obtain skilled nursing care benefits,
- And receive IVF coverage, up to $25,000 annually.
If you’re enrolled in Standard and don’t use those benefits, you could save some serious money switching to Basic or FEP Blue Focus, and you’ll get to keep your existing BCBS in-network providers. Families switching from Standard to Basic would save $2,843 next year, and families switching from Standard to FEP Blue Focus would save $8,360.
Self-Plus-One vs Self & Family enrollment
Married couples and two-person families can enroll as either self-plus-one or self & family. Most of the time, self-plus-one is cheaper, but there are 38 FEHB plans where self & family enrollment is less expensive.
There’s a lot of money at stake based on your enrollment decision. For example, a two-person family considering Kaiser High (E3) in the Washington, D.C. area, Kaiser High (NZ) in Fresno, California, or Kaiser High (59) in northern California can save $76.29 biweekly enrolling as self & family compared to self-plus-one. That adds up to $1,984 annually.
You can see the differences by going to the last page of the plan’s official FEHB brochure. Look for the enrollee share of premium and choose the enrollment option that’s cheaper. You’ll receive the same benefits regardless of how you enroll.
FEDVIP premiums
FEDVIP premiums have historically increased at a much lower rate compared to FEHB plans, and this remains true in 2027. Dental plan premiums will go up 1% on average, and vision plan premiums will increase by 1.6%.
In summary
FEHB premiums are rising an average of 10.9% in 2027, but many plans will see even steeper increases. While the premium is just one factor in choosing a health plan, it’s a guaranteed expense that directly affects your budget. That’s why it’s essential to review how your current plan is changing and explore whether another option might offer better value for you and your family.
However, what you’ll pay for healthcare next year goes beyond just your premium. You must also factor in out-of-pocket costs. Our guide will be released before Open Season starts and ranks all FEHB plans on estimated yearly cost, the combination of premium and likely out-of-pocket expenses based on your profile
Make sure to check in-network providers, prescription drug coverage, and any unique benefits that matter to you before switching.
The 2027 FEHB Open Season runs from Nov. 9 to Dec. 14, giving you time to compare, evaluate, and make the best choice for your needs.
I’m answering your FEHB questions as part of Federal News Network’s Open Season Exchange on Nov. 9. If you have questions about FEHB coverage, how Medicare works with FEHB, or anything else healthcare related you’d like to learn more about, you can submit them here. We’ll try to answer as many as we can.
Source here: